ESG COMPLIANCE
A CSRD double materiality assessment you can defend
For groups above the CSRD thresholds of 1,000 staff and €450M turnover. Greenly scores materiality on a 400-IRO benchmark and produces the XBRL statement your auditor reviews.


TRUSTED BY 4,000 CLIENTS, FROM SMB TO ENTERPRISE


Case Study


Case Study

Where post-Omnibus CSRD still breaks

The rules moved under you
Scope, ESRS and deadlines all changed after Omnibus. Work done under the old rules now has to be remapped to the simplified ESRS.

Materiality you can't defend
Workshop-based double materiality assessments take months and score the same IRO differently from one session to the next. Disclosing non-material topics has also become a compliance breach.

Entity data in spreadsheets
Finance, HR and sites each report their own way. With no consolidation rules and no audit trail, the auditor asks who entered what.
Check if your company is affected by the CSRD after Omnibus
Confirm your scope, then score materiality
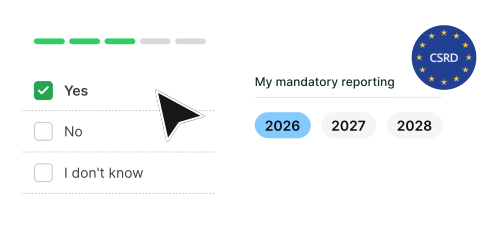
 Test each entity against the relevant thresholds:
EU parents: over 1,000 employees and €450M net turnover. First report: FY2027.
Non-EU parents: over €450M EU turnover for two years, plus an EU entity above €200M. First report: FY2028.- Start the double materiality assessment from a benchmark of 400 IROs for your sector and screen out non-material topics top-down.
- Score on fixed brackets, so a re-run gives the same matrix. Genuine edge cases go through a logged override.

Collect and consolidate entity data
- Turn each material ESRS disclosure into a data request for the right owner, with AI-guided questions.
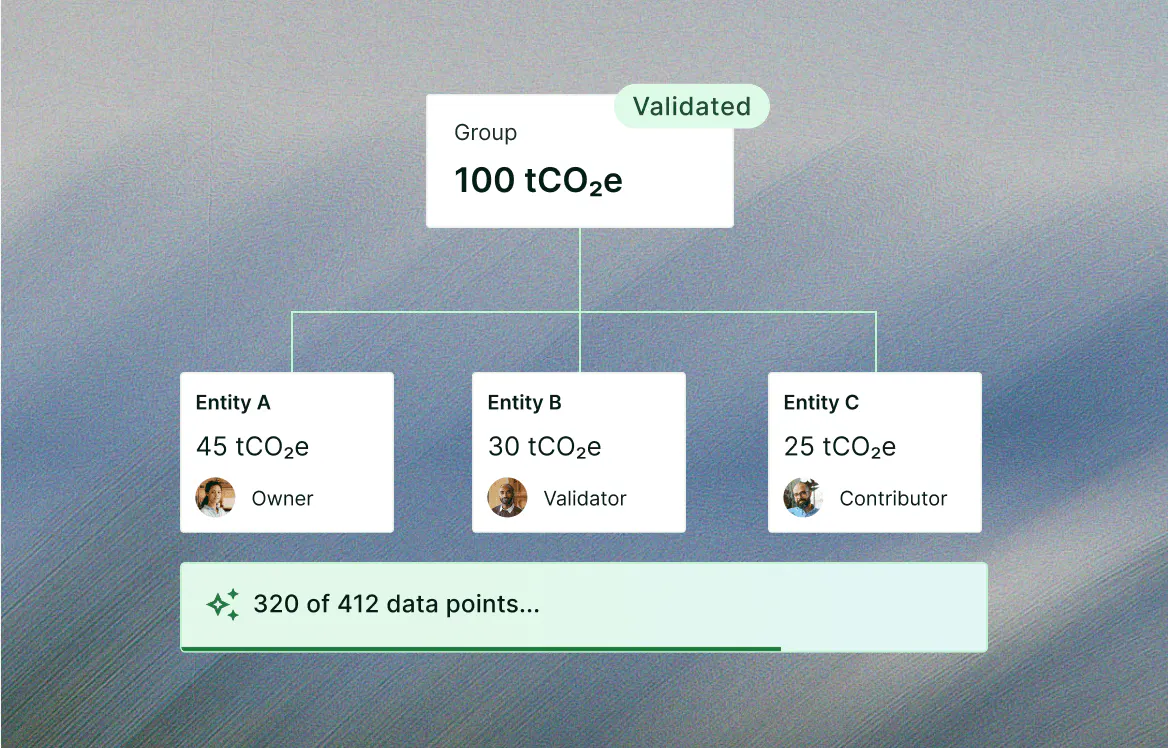
- Assign Owner, Validator, Contributor and Auditor roles per data point. Every entry and edit is logged.
- Consolidate up the corporate tree with explicit rules per metric, so nothing is double-counted.
- Keep supplier requests within the VSME value-chain cap: 23 data points, or 9 for micro-suppliers.
Close the gaps before your auditor does
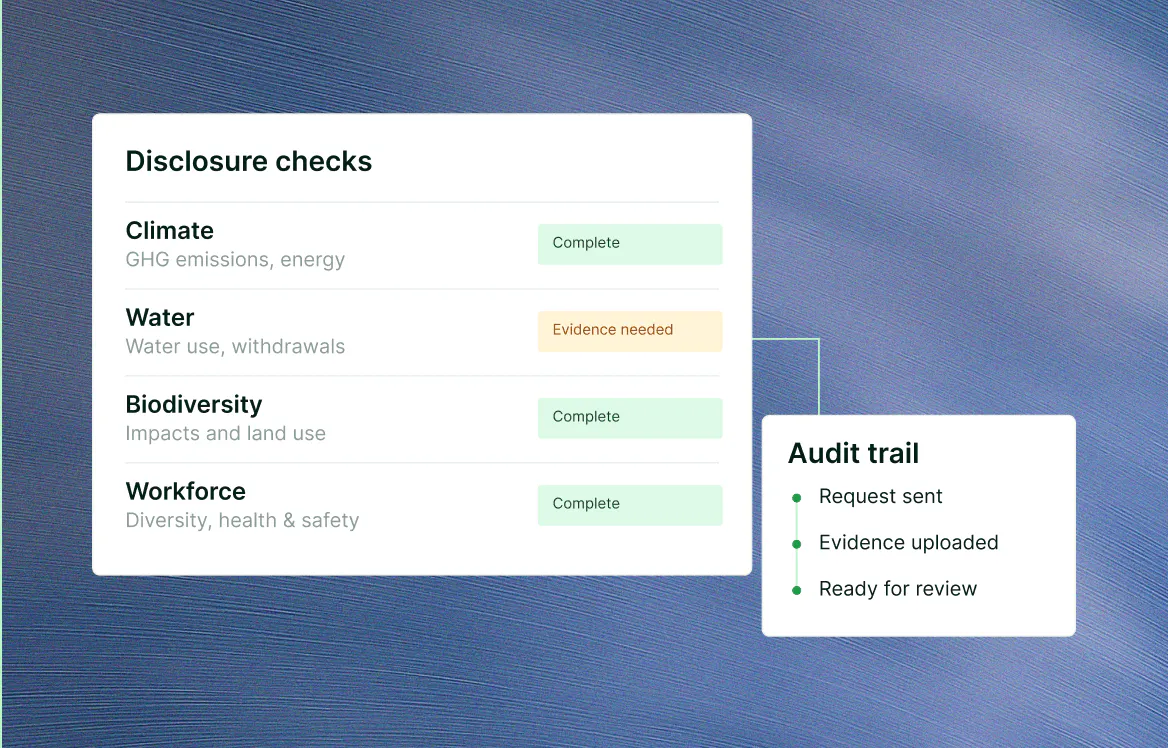
- An ESRS gap analysis shows which material disclosures still lack data, owners or evidence.
- Internal data audits flag inconsistent or unsupported values before they reach the statement.
- Scheduled check-ins with Greenly CSRD experts keep the project on track for its filing date.
- Your auditor gets read-only access to the trail behind every reported figure.
Generate your audit-ready statement
- Export the sustainability statement in XHTML with XBRL tagging, ready for your annual report.
- Produce the board summary from the same validated dataset as the statement.
- Reuse the data for EcoVadis and IFRS S2 requests from customers without collecting it twice.

Below CSRD thresholds? Report with VSME
Omnibus removed most companies from CSRD, but customers, banks and investors still ask for sustainability data. Those requests are now capped by the VSME standard: 23 data points for companies up to 1,000 employees.
Still have questions about CSRD?
Have more questions? Check out our complete FAQs in the Knowledge Base to get the answer you’re looking for.
The Corporate Sustainability Reporting Directive (CSRD) requires the largest companies operating in the EU to publish audited sustainability information in their annual management report. The Omnibus I Directive, in force since 18 March 2026, narrowed CSRD scope to companies with over 1,000 employees and over €450M net turnover, and simplified the reporting standards (ESRS).
EU companies must report under the CSRD if they exceed 1,000 employees on average and €450M net turnover. Both criteria must be met.
EU companies newly in scope report on FY2027 data, published in 2028. Non-EU groups report on FY2028 data in 2029. Member states must transpose the Omnibus changes by 19 March 2027.
Companies that reported on FY2024 data and remain above the new thresholds keep reporting. Companies that fall below the new thresholds may be exempted for FY2025 and FY2026, depending on whether their member state applies the transition exemption.
A double materiality assessment (DMA) identifies which sustainability topics a company must report under the CSRD. It scores each impact, risk and opportunity (IRO) on two axes: the company's impact on people and the environment, and the financial effect of sustainability issues on the company. Only topics found material are disclosed.
Mandatory data points fell by more than 60% and total data points by more than 70%. Voluntary data points were removed, and a top-down materiality approach is encouraged.
Yes, within a cap. Companies in CSRD scope can request from suppliers with fewer than 1,000 employees only the information set out in the voluntary VSME standard: up to 23 data points, or 9 for companies with 10 employees or fewer. Suppliers must be told about this limit and can refuse requests beyond it.
Yes. CSRD sustainability statements require limited assurance from an external auditor or accredited assurance provider. The planned move to reasonable assurance has been put on hold.
Penalties are set by each member state in its national transposition law, so they vary by country. Check the law of each country where your group files.