ESG COMPLIANCE
CSRD Reporting:
Simplified for Success.
Master your compliance with a platform that transforms reporting into a key driver for sustainable growth.


TRUSTED BY 4,000 CLIENTS, FROM SMB TO ENTERPRISE


Case Study


Case Study


Integrated EFRAG-Compliant Scoring
Automated industry-specific materiality assessments to ensure your reporting remains fully aligned with EFRAG standards.
AI-Powered ESRS Data Collection
Streamline data mapping with AI-guided questions and tools to collect relevant ESRS information effortlessly.
Automated xHTML & XBRL Reporting
Generate audit-ready reports in xHTML format, complete with integrated XBRL tagging for direct, seamless regulatory submission.

Expert Guidance at Every Stage
Partner with Greenly’s CSRD and Climate Experts through dedicated training, regular check-ins, and specialised tools to accelerate your progress.
The Only End-to-End CSRD Solution
With CSRD on the horizon, now’s the time to prepare and avoid wasting hours on compliance. Greenly’s platform offers expert guidance and tailored tools to ensure total regulatory readiness.

Greenly ensures dedicated support at every step from experts trained directly by AFNOR and APAVE for CSRD auditing
Quickly check your company’s
CSRD requirements
Cut CSRD Reporting Time From 1,000 Hours to Under 100
With CSRD on the horizon, now’s the time to prepare and avoid wasting hours on compliance. Greenly’s platform provides the expert guidance and specialised tools necessary to ensure total regulatory readiness.
An EFRAG-Aligned Foundation for Total Compliance

- Rigorous Double Materiality Methodology engineered by in-house experts specifically for CSRD audit standards.
- Automated gap analysis to define and map the entire ESG data journey.
- Actionable insights following gap analysis to ensure full regulatory compliance.
- CSRD-trained experts available to provide guidance and support at every step of the process.
- ISSA 5000-aligned third-party auditor access to the Gap Analysis tool
- Integrated AI Assistant for real-time ESG guidance and support.
Comprehensive Coverage of 320+ ESRS Data Points

- Fully-integrated GHG platform for precise Scope 1, 2 and 3 assessments and Decarbonisation Transition Plan
- Automatic calculation of quantitative data points through end-to-end modules (i.e. Waste, HR, etc)
- AI-powered narrative assistance that generates reporting insights directly from uploaded ESG data and API connections.
- Sustainability performance monitoring and tracking in a single platform
- AI-powered internal audits, verified by sustainability experts to prevent errors and irregularities
Generate Fully Automated, Audit-Ready Reports

- Flawless formatting with integrated XBRL tagging and export-ready xHTML files.
- Seamlessly align your data with global ESG standards, including CDP, ISSB, SEC, and SFRD
- Directly integrate EU Taxonomy exports into the final Sustainability Report.
- Automatically generate and export Verification Reports finalised by third-party auditors.
- Grant ISSA 5000-aligned access to third-party auditors while monitoring auditing progress in real-time.
Streamlined Collaboration Across Functions and Entities

- Coordinated workflows to manage tasks, deadlines, and teams across multiple entities via an automated notification system.
- Scalable multi-entity architecture built for organisations of any size, featuring granular access control.
- Digital audit trails with time-stamped records for transparent accountability
- Integrated CRM system to eliminate manual follow-up and maintain accountability through automatic notifications.
- Access to third-party auditors to give recommendations and feedback on data requirements & data quality level
- On-demand AI assistance to streamline workflows and optimise data processing.
Future-Proof Your Business,
Master CSRD Compliance Today.
Deadlines are now. Become compliant to avoid fines.
What is the CSRD Directive?
The CSRD, or "Corporate Sustainability Reporting Directive," is a groundbreaking European directive that mandates certain companies to provide annual non-financial reporting.
Its primary goal is to enhance transparency by disclosing comprehensive and reliable information on companies' environmental and social impacts.
 Pre-report
- Double Materiality Assessment and Due Diligence
- EU taxonomy system including XBRL tagging
- Governance-related information (management of sustainability risks)
 Post-report
- Mandatory third-party auditing
- Digitalisation of sustainability reports in the The European Single Electronic Format (ESEF)
Does it apply to my company?
Following the 2026 Omnibus simplification package, the CSRD focuses on the largest EU market players, impacting approximately 15,000 companies, including the following:

Companies previously subject to the NFRD
- At least 500 employees
- More than 40 million euros turnover
- More than 25 million euros in the balance sheet
Report by 2025
Based on 2024
Report by 2025
Based on 2024

Large Enterprises
(Both listed and unlisted)
- At least 1,000 employees
- And either: 450 million euros turnover or 25 million euros in the balance sheet
Report by 2026
Based on 2025
Report by 2028
Based on 2027

Small and Medium sized Companies
(European and non-European)
- Listed SMEs are exempt and no longer required to report.
- Protected Status: Companies under 1,000 employees only need to use the Voluntary SME Standard (VSME) if asked for data by large partners.
- 900k euros turnover
Report by 2027
Based on 2026

Non-EU Parent Companies
- Over 450 million euros of EU turnover annually for 2 consecutive years
- Must have an EU subsidiary with 1,000+ employees or an EU branch with €200 million+ turnover
Report by 2029
Based on 2028
Report by 2029
Based on 2028
What are the data requirements?
European Sustainability Reporting Standards (ESRS) are the essential guidelines for CSRD reporting requirements. These include cross-cutting standards, such as ESRS 1 and ESRS 2, as well as topic-specific standards.
ESRS 1
ESRS 1 establishes the general principles to follow when preparing sustainability reporting.
- Double materiality assessment
- Sustainability due diligence
- Supply and value chain
- Timeline
ESRS 2
ESRS 2 outlines the general disclosure requirements and mandatory baseline disclosures, regardless of materiality assessment outcomes. It also defines the structure for topical standards, grouped into four main sections:
- Governance: Disclosure Requirements 1-5
- Strategy: SBM 1-3
- Impacts, risks and opportunities - IRO 1-2 (based on Double Materiality Assessment)
- Metrics and targets

Environnement

Social

Governance
Not Impacted by CSRD? The VSME Standard is the Solution
Your company may not be impacted by the CSRD, but your largest clients are. Since 2025, they have been required to collect sustainability data from their entire value chain, including you.
The VSME standard, a must-have
- 90% less effort than the full CSRD
- Standardised format recognised by all large companies
- No mandatory audit (unlike the CSRD)
- Competitive advantage: be ready before your competitors
Why act now?
Leaders are preparing while their competitors wait. Within the next 12-18 months, your clients will demand this data. those unable to provide it risk being replaced within the value chain.
With Greenly
- Simplified and guided questionnaire
- VSME report generated in one click
- Comprehensive training and support
- Trusted by over 4,000 companies.
Still have questions about CSRD?
Have more questions? Check out our complete FAQs in the Knowledge Base to get the answer you’re looking for.
The Corporate Sustainability Reporting Directive (CSRD) requires the largest companies operating in the EU to publish audited sustainability information in their annual management report. The Omnibus I Directive, in force since 18 March 2026, narrowed CSRD scope to companies with over 1,000 employees and over €450M net turnover, and simplified the reporting standards (ESRS).
EU companies must report under the CSRD if they exceed 1,000 employees on average and €450M net turnover. Both criteria must be met.
EU companies newly in scope report on FY2027 data, published in 2028. Non-EU groups report on FY2028 data in 2029. Member states must transpose the Omnibus changes by 19 March 2027.
Companies that reported on FY2024 data and remain above the new thresholds keep reporting. Companies that fall below the new thresholds may be exempted for FY2025 and FY2026, depending on whether their member state applies the transition exemption.
A double materiality assessment (DMA) identifies which sustainability topics a company must report under the CSRD. It scores each impact, risk and opportunity (IRO) on two axes: the company's impact on people and the environment, and the financial effect of sustainability issues on the company. Only topics found material are disclosed.
Mandatory data points fell by more than 60% and total data points by more than 70%. Voluntary data points were removed, and a top-down materiality approach is encouraged.
Yes, within a cap. Companies in CSRD scope can request from suppliers with fewer than 1,000 employees only the information set out in the voluntary VSME standard: up to 23 data points, or 9 for companies with 10 employees or fewer. Suppliers must be told about this limit and can refuse requests beyond it.
Yes. CSRD sustainability statements require limited assurance from an external auditor or accredited assurance provider. The planned move to reasonable assurance has been put on hold.
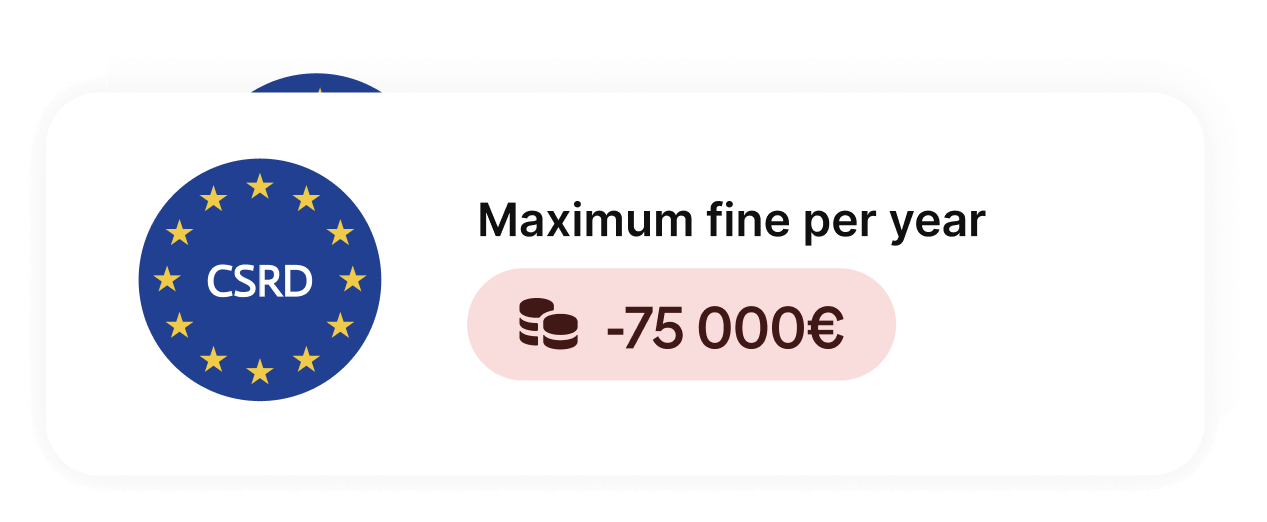
Penalties are set by each member state in its national transposition law, so they vary by country. Check the law of each country where your group files.