Carbon Footprint Management Software: UK Top 10
1 min
Level
Compare ten carbon footprint management software options for UK firms, from SECR and UK SRS reporting to Scope 3 tracking and decarbonisation.
By Kara Anderson, UK Copywriter,
Updated by Agnès Potier-Murphy, on 12/10/2026
IFRS S2 is the ISSB's standard for climate-related disclosure, and it exists for a specific reason: investors no longer take a balance sheet at face value when climate risk is involved. They want evidence that a business can hold up under a warmer, more volatile set of conditions, and that's what S2, paired with the broader IFRS S1 framework for sustainability-related risks and opportunities, is designed to provide. Rather than a standalone sustainability exercise, both standards tie that evidence directly into the financial reporting companies already produce.
S2 in particular isn't starting from a blank page. It builds on TCFD (the Task Force on Climate-related Financial Disclosures), which had already become the de facto standard for climate reporting before the ISSB formalised it into IFRS S1 and S2 in 2023. Adoption since then has moved quickly: as of August 2026, 35 jurisdictions had taken up the standards on a mandatory or voluntary basis, with another 11 working toward it, according to the IFRS Foundation's own tracker, which is updated on a rolling basis. The UK sits among the more advanced adopters via its own UK SRS, while the US remains one of the larger holdouts; across most of those 35-plus markets, though, S1 and S2 reporting is simply becoming standard practice.
What the IFRS Foundation and the ISSB do
Why IFRS introduced sustainability disclosure standards in the first place
What IFRS S1 and IFRS S2 require companies to disclose
How the standards approach materiality, risk, and financial impacts
When the standards apply and how adoption works across different countries

Climate and sustainability risk used to sit outside the numbers investors actually relied on. That's changed: a company's exposure to supply chain disruption, a sudden shift in regulation, or its ability to hold up as the climate changes now factors directly into how it's assessed, and for a long time there was no consistent way to get a straight answer on any of it.
Part of the problem was simply fragmentation. Every jurisdiction, and often every company, defined and reported these risks differently, which made comparison close to impossible and left companies carrying a compliance burden with little payoff in investor trust.
The IFRS Foundation's 2020 consultation set out to test whether the market wanted something better, and the response left little doubt: investors, regulators and standard-setters alike wanted one reliable, comparable baseline. That consultation is what eventually produced the IFRS Sustainability Disclosure Standards.
The IFRS Foundation isn't new to setting global rules. It's long been behind international accounting standards, the shared framework that lets an investor anywhere trust a set of accounts prepared anywhere else, now required across more than 160 jurisdictions and treated as the default for how cross-border business gets reported.

The Foundation’s mission is built on a straightforward principle: better information leads to better decisions. By providing a common financial language, they’ve brought a level of transparency and efficiency to capital markets that simply didn't exist before.
That same discipline is now being extended to sustainability. The logic doesn't change: bring the same consistency and comparability that already exists for financial data to ESG information, so that a sustainability disclosure gets read with the same seriousness, and carries the same real financial weight, as anything on the balance sheet.
The body actually responsible for IFRS S1 and S2 is the ISSB, set up by the IFRS Foundation in 2021 as the sustainability counterpart to the International Accounting Standards Board (IASB). Where the IASB owns the traditional accounts, the ISSB owns the sustainability-related information now shaping how a company gets valued.
Its mandate is deliberately a floor, not a ceiling: a clear, comparable framework for how climate risk and social change feed into cash flow, resilience and long-term performance, that individual jurisdictions then build on rather than replace. The UK is a good example of how that plays out in practice, layering its own UK SRS on top of the ISSB baseline rather than inventing something separate (more on that below). Wherever a company is based, the underlying facts an investor is looking at stay the same; it's only the local wrapper around them that varies.

Between the two, IFRS S2 is the standard that deals with climate specifically, while IFRS S1 lays down the general sustainability disclosure requirements underneath it. Together they form what the ISSB calls the IFRS Sustainability Disclosure Standards: a single framework for reporting the sustainability-related risks and opportunities bearing on a company's financial performance.
Applying both in practice means holding climate and sustainability disclosures to the same standard as the financial statements: governance, strategy, risk management, and metrics, sitting right alongside the numbers investors already use. You'll sometimes see the pair called the "IFRS ESG standards" instead, a slightly loose label, since the ISSB's own focus is specifically financial materiality rather than ESG in the broader sense, but the two terms get used interchangeably often enough to be worth knowing they're not strictly identical.
No company operates in isolation, and IFRS S1 starts from that premise: its financial position is shaped by its relationships with stakeholders, wider society and the environment across the whole value chain, not just what happens inside its own walls.
The standard requires companies to disclose the sustainability-related risks and opportunities that directly impact their ability to generate cash over the short, medium, and long term. Whether it’s a dependency on a scarce natural resource or a vulnerability in a global supply chain, these factors have a tangible effect on a company's cost of capital and its attractiveness to investors.
That doesn't mean disclosing everything, though. The standard is deliberately proportionate: if a piece of information couldn't reasonably sway an investor's decision, it doesn't belong in the report. That keeps the focus on what's financially material, rather than turning into an exhaustive ESG checklist.
To ensure investors get a complete picture, both IFRS S1 and S2 are organised around four core pillars, the same four at the heart of TCFD, so the structure should already feel familiar to anyone who's reported under that framework before. These pillars aren't just a checklist; they describe how a business actually integrates sustainability into its DNA:
Governance
Who is in charge?
Shows how the board and leadership oversee sustainability risks - including roles, controls, and the processes that drive accountability at the top.
Strategy
How does this change the plan?
Explains how sustainability factors influence the business model and long-term decisions - the big picture of how the company plans to stay resilient.
Risk management
How are threats spotted?
Covers how sustainability risks are identified and prioritised - and how those steps are built into the company’s wider risk management system.
Metrics & targets
How is progress measured?
Sets out the metrics used to track performance, the targets a company has set (or must meet), and a clear-eyed view of progress so far.
At the heart of IFRS S1 is the principle of materiality. In short: if a piece of information could change an investor’s mind or influence their decision, it must be disclosed. Whether it’s omitted, buried, or misrepresented, if it matters to the financial story of the company, it belongs in the report.
This is fundamentally about quality: the standard demands a complete, neutral, and accurate account of a company's position. In practice, that means applying the same level of rigour to sustainability data that has always been reserved for the balance sheet.
To make this transition easier, the reporting mechanics (how often you report, how you handle estimates, how you show year-over-year comparisons) are designed to mirror traditional financial statements. For companies already used to IFRS accounting, these requirements will feel familiar, allowing sustainability and financial data to sit naturally side-by-side.
While S1 provides the framework, IFRS S2 zooms in on the most pressing financial challenge of our time: climate change. It’s structured around the same four pillars we just covered, but it adds a sharp focus on the specific ways climate shift impacts a company’s outlook.
Under S2, companies are expected to look at climate through two distinct lenses:
To give investors a clear view of the future, S2 requires transparency across the business:
The shift to these standards is already underway: IFRS S1 and S2 became effective for reporting periods starting in January 2024, with the first aligned disclosures reaching the market the following year.
By 2026, the "first-look" period is over. For most organisations now in scope, S1 and S2 reporting sits inside the normal annual cycle, whether that's a deliberate strategic choice or simply what regulation now requires.
The ISSB itself has no power to make anything compulsory; it sets the baseline, and it's down to national and regional regulators to decide whether to require it.
What's changed since launch is the pace: jurisdiction after jurisdiction has moved to adopt or align with the framework, and if anything that's only sped up. For companies, the mandatory question tends to come down to one of two routes:
There's more to adopting IFRS S1 and S2 than ticking a compliance box. A more disciplined approach to data is itself the benefit, and it's what gives companies a clear route to both regulatory stability and investor confidence.
A universal language for capital
Using an investor-focused baseline helps companies “speak the same language” across borders — making disclosures clearer and comparisons across sectors and countries far more credible.
Future-proofing your reporting
As more jurisdictions align with ISSB standards, early adoption helps companies stay ahead — and avoid costly reporting whiplash when new rules arrive.
From storytelling to strategy
These standards push disclosures toward financially grounded insights. The focus on material risks and opportunities makes reporting leaner — and more useful for capital allocation decisions.
Leveraging what you’ve built
Since April 2022, TCFD-aligned disclosure has been mandatory for the UK's largest companies. IFRS S1 and S2 build on it, with SASB and CDSB folded in, so companies already meeting that obligation are evolving towards S1/S2 compliance rather than starting from scratch.
Cutting through complexity
For multinationals, the goal is "report once, use often." A shared global foundation reduces duplication — even when local requirements add extra layers.
IFRS S1 is the broader standard: it covers how a company identifies and reports on any sustainability risk or opportunity that's material to its finances. IFRS S2 sits underneath it and narrows the focus to climate specifically, with more detailed requirements around physical risk, transition risk, and greenhouse gas emissions. In practice, the two are almost always applied together, since S2 depends on the general groundwork S1 lays down.
Not directly, but a UK-specific equivalent now exists. In February 2026, the UK government published the UK Sustainability Reporting Standards (UK SRS), the UK-endorsed versions of IFRS S1 and S2, available for voluntary use. Following its consultation, which closed in March 2026, the FCA has proposed applying UK SRS-aligned disclosure rules to listed companies from 1 January 2027. For a full breakdown of what the UK SRS covers and its expected timeline, see our dedicated guide to the UK Sustainability Reporting Standards.
As of August 2026, the IFRS Foundation's own tracking put adoption at 35 jurisdictions on a mandatory or voluntary basis, with 11 more working toward it, concentrated particularly across Asia-Pacific, the Middle East and parts of Latin America. The UK is one of the more advanced adopters via its own UK SRS (see above); the US sits at the other end, with no federal mandate for ISSB alignment, though individual states, California included, are moving ahead on their own climate disclosure rules.
They serve different, but complementary, purposes, and the distinction matters slightly differently for a UK business than it does elsewhere. IFRS S1 and S2 focus on financial materiality: what sustainability and climate issues matter for enterprise value and investor decision-making. CSRD/ESRS apply a double materiality approach instead, covering both financial impacts and a company's own impact on society and the environment. The UK itself sits outside CSRD's scope, but plenty of UK groups have EU subsidiaries or operations that fall within it regardless, so reporting under both frameworks in parallel is still a live issue for them. Fewer of those companies face that double-reporting question than a year ago, though: the EU's Omnibus I Directive, in force since March 2026, cut CSRD's mandatory scope by roughly 90% and simplified ESRS alongside it.
Not in the same way as large companies. The ISSB standards are not designed for small, non-listed SMEs, and most jurisdictions applying them are doing so with proportionality thresholds. That said, SMEs that sit within large value chains may still be asked to provide data that supports IFRS-aligned disclosures at the group level.
IFRS S2 requires disclosure of absolute gross Scope 1, 2, and 3 GHG emissions as a core metric under paragraph 29(a) of the standard, on the same basis as Scope 1 and 2 — it isn’t a separate, ongoing materiality test specific to Scope 3. The main relief is transitional: entities may omit Scope 3 figures in their first annual reporting period under IFRS S2. In December 2025, the ISSB issued targeted amendments to these requirements, effective for reporting periods beginning on or after 1 January 2027 (early application permitted): entities may now limit measurement and disclosure of Scope 3 Category 15 (investments) to financed emissions as defined in IFRS S2. Scope 3 is increasingly unavoidable for many sectors, but companies should track this 2027 effective date closely.
The standards themselves do not mandate assurance. However, in practice, many regulators are introducing or considering assurance requirements for sustainability disclosures. Investors also increasingly expect externally assured climate and sustainability data.
That depends on jurisdiction, size, and capital market exposure. IFRS S1 and S2 are primarily designed for capital markets, so they are most relevant to: listed companies, companies with external investors, and companies seeking financing or preparing for future listing. However, many large private companies are choosing to align voluntarily, particularly where lenders, insurers, or investors expect ISSB-aligned climate and sustainability information.
TCFD wound down as an active body in 2023, once the ISSB published IFRS S1 and S2 and took over responsibility for monitoring climate-related financial disclosure. Its substance didn't disappear, though: IFRS S2 carries the same four pillars (governance, strategy, risk management, and metrics & targets) forward almost unchanged. In practice, this means a company already reporting under TCFD has done most of the groundwork needed for IFRS S2.

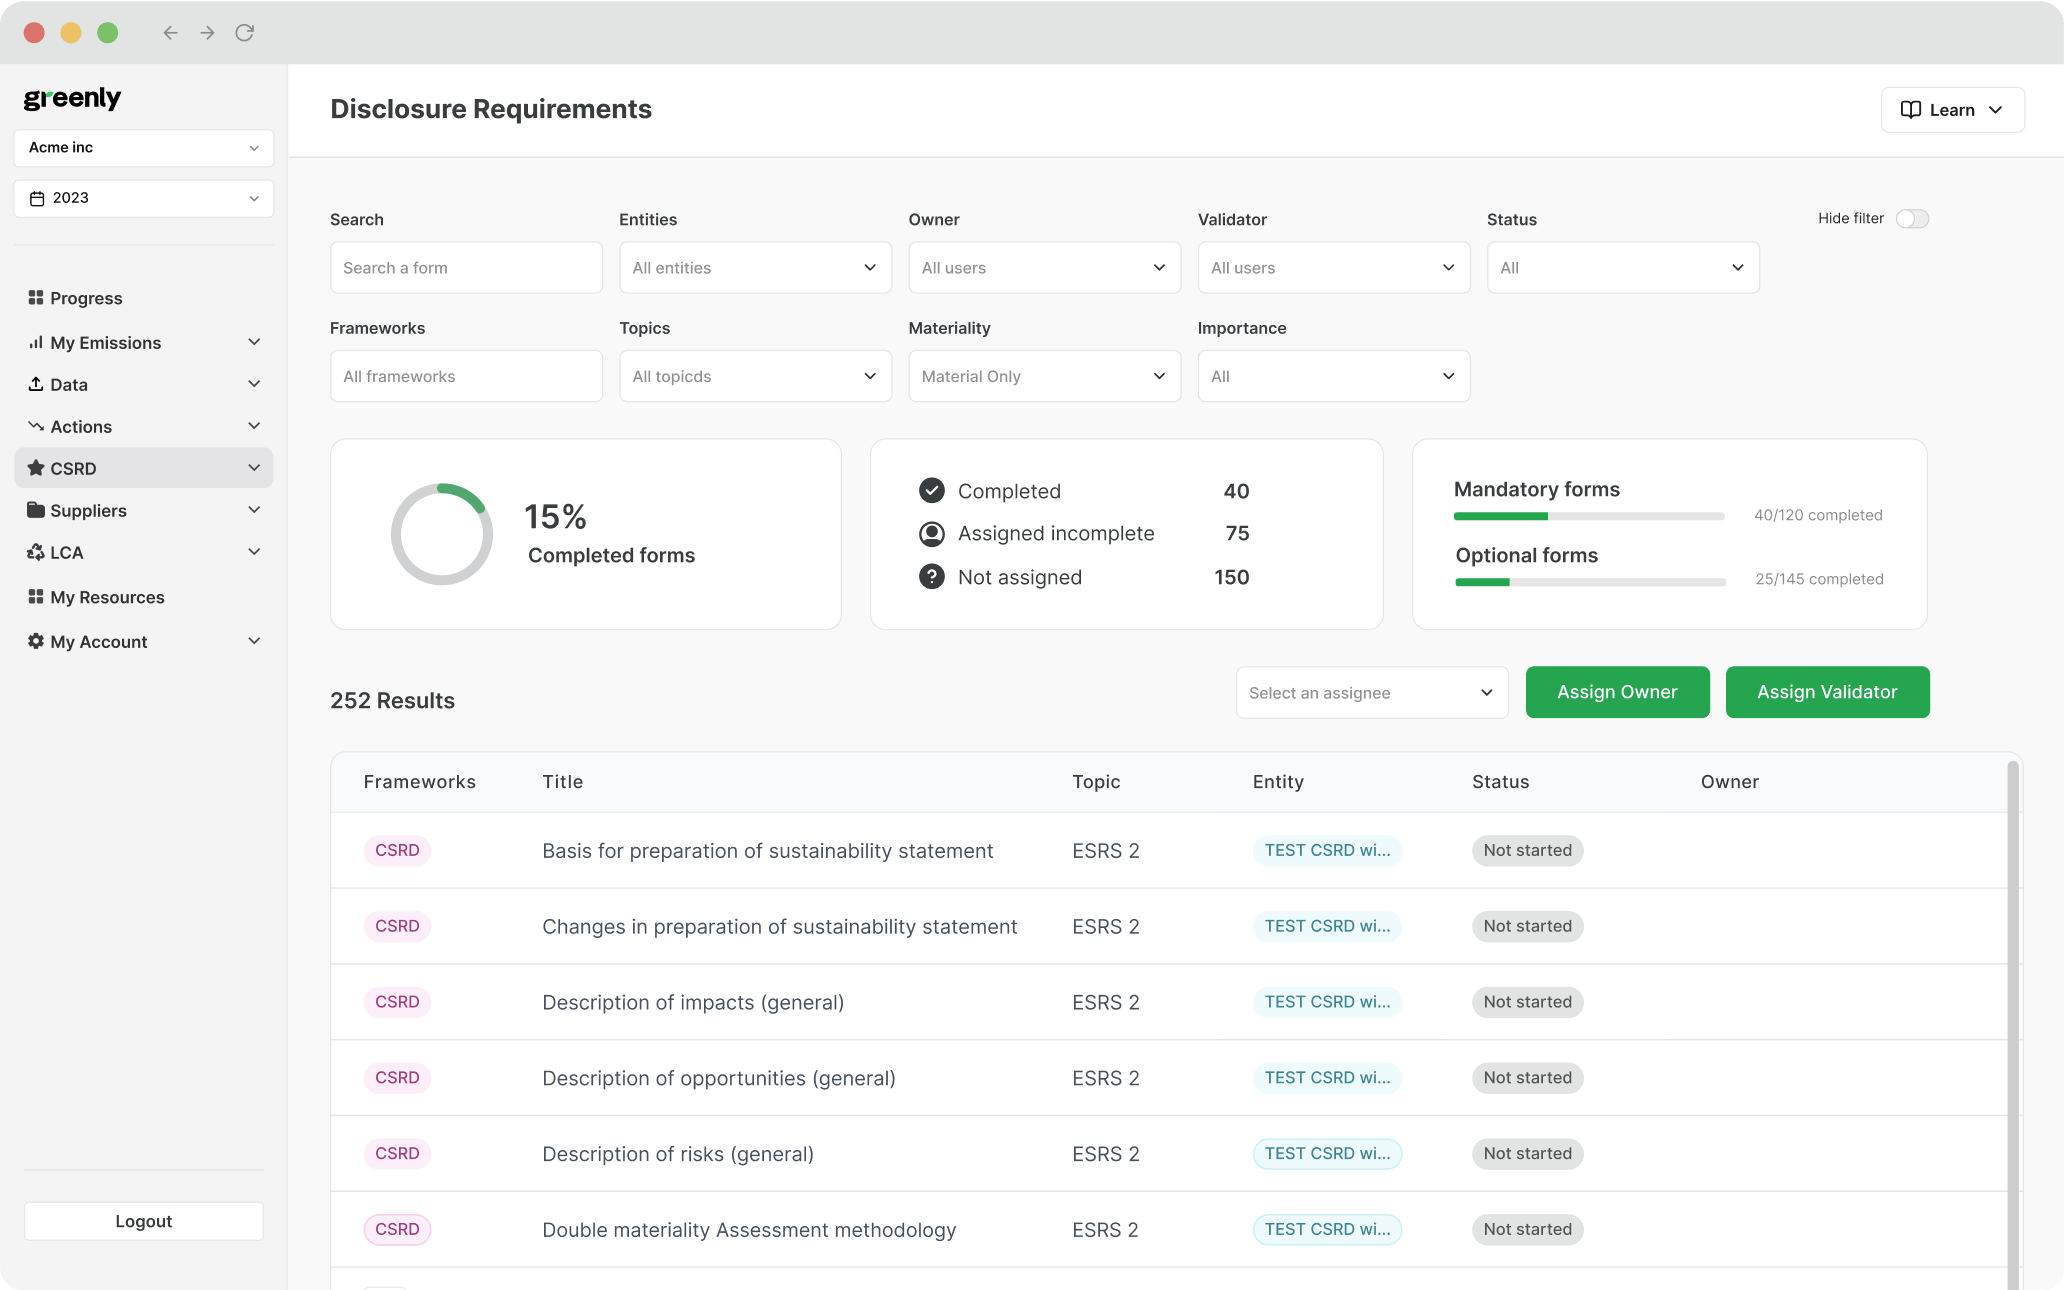
From TCFD-era reporting through to full IFRS S1 and S2 disclosure, and everything these standards touch across a broader ESG programme, Greenly brings it all together on one platform:
Greenly, "Our Guide to European Sustainability Reporting Standards (ESRS),"

Greenly, "What is the Corporate Sustainability Reporting Directive (CSRD)?,"
Greenly, "What is a materiality assessment?,"
Greenly, "What is the International Sustainability Standards Board (ISSB)?,"
IFRS, "IFRS S1 General Requirements,"
IFRS, "IFRS S2 Climate-related Disclosures,"
IFRS Foundation, "ISSB issues targeted amendments to IFRS S2"
IFRS Foundation, "IFRS Sustainability Disclosure Standards around the world,"
IFRS Foundation, "International Sustainability Standards Board (ISSB),"
IFRS Foundation, "Consultation Paper on Sustainability Reporting,"
U.S. Securities and Exchange Commission, "SEC Proposes Rescission of Climate-Related Disclosure Rules,"
California Air Resources Board, "Climate-Related Financial Risk,"
European Union, Directive (EU) 2026/470 (Omnibus I)
European Commission, "Commission adopts revised sustainability reporting standards,"
S&P Global Sustainable1, "Where does the world stand on ISSB adoption? (August 2026),"
Share this article


More Articles
View allCarbon Footprint Management Software: UK Top 10
Compare ten carbon footprint management software options for UK firms, from SECR and UK SRS reporting to Scope 3 tracking and decarbonisation.
Decarbonisation: what it is and why it matters
What is decarbonisation and why is it urgent? Learn practical steps companies can take to support the global move toward net zero emissions.
The Carbon Border Adjustment Mechanism (CBAM)
In this article, we break down what the EU CBAM is, how it works, and what businesses need to do to comply.
Impacts, Risks, and Opportunities (IRO) for CSRD Reporting
In this article, we’ll break down what IROs are, how to identify and assess them, and what CSRD requires in terms of disclosure.
