ESG COMPLIANCE
CSRD reporting for US companies with EU operations
Over €450M in EU revenue? Greenly maps which entities report and when, scores double materiality, and builds the XBRL statement on top of the SB 253 data you already hold.


TRUSTED BY 4,000 CLIENTS, FROM SMB TO ENTERPRISE


CSRD issues US groups still face after Omnibus

Two scope tests, one group
EU subsidiaries may report from FY2027, the US parent from FY2028. Each entity needs its own answer on who files what, and when.

Materiality you can't defend
Workshop-based assessments take months and can rate the same IRO differently on a second pass. Reporting on topics that aren’t material is itself a breach.

Another framework, the same data owners
SB 253, IFRS S2, CDP, EcoVadis, and now ESRS. Each sends your team back to the same people, cycle after cycle.
Check if your company is affected by the CSRD after Omnibus
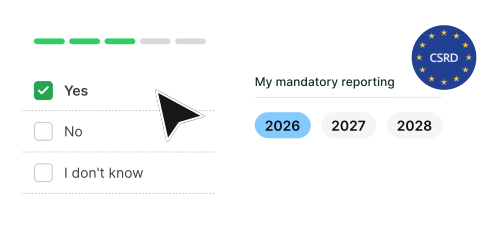
Confirm your scope, then score materiality
 Test each entity against the CSRD thresholds:
• EU parents: over 1,000 employees and over €450M in net revenue. First report: FY2027.
• Non-EU parents: over €450M in EU revenue for two years, plus an EU entity above €200M. First report: FY2028.- Build the DMA on a 400-IRO sector benchmark and screen out non-material topics top-down.
- Score on fixed brackets, so a re-run gives the same matrix. Genuine edge cases go through a logged override.

Collect and consolidate entity data
- Start from the emissions data you already hold for SB 253 or IFRS S2, then fill only the ESRS gaps.
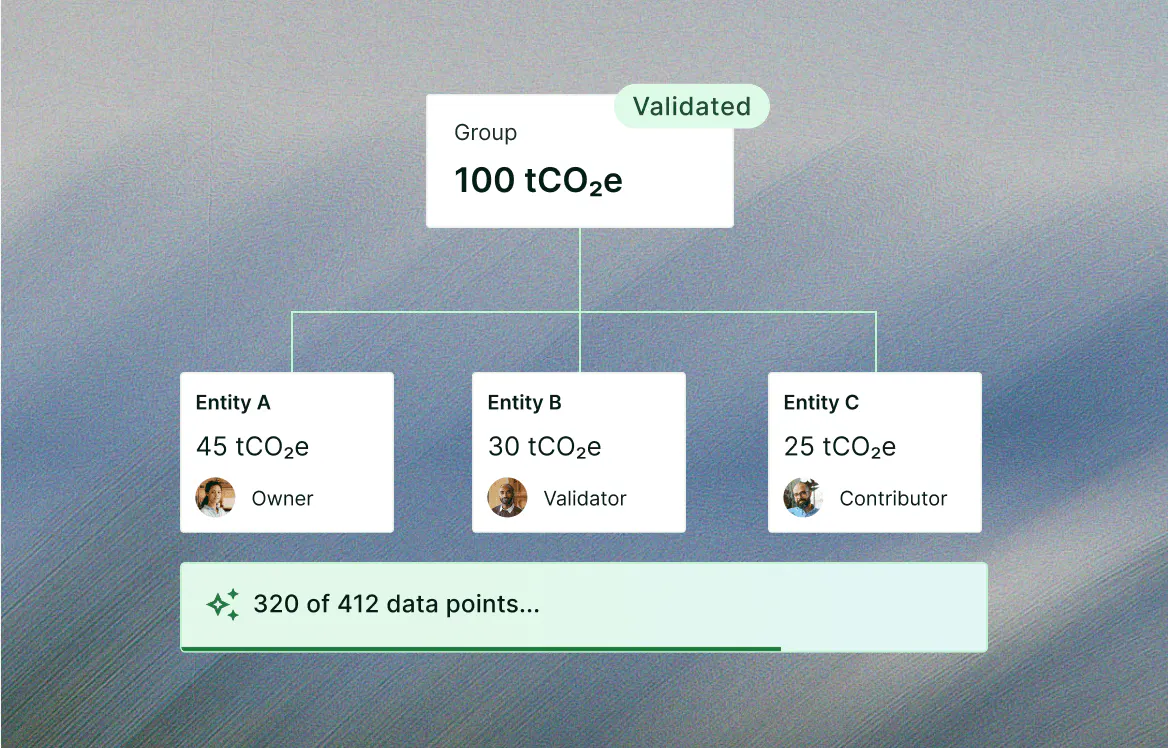
- Assign Owner, Validator, Contributor and Auditor roles per data point. Every entry and edit is logged.
- Consolidate up the corporate tree with explicit rules per metric, so nothing is double-counted.
- Keep supplier requests within the VSME value-chain cap: 23 data points, or 9 for micro-suppliers.
Close the gaps before your auditor does
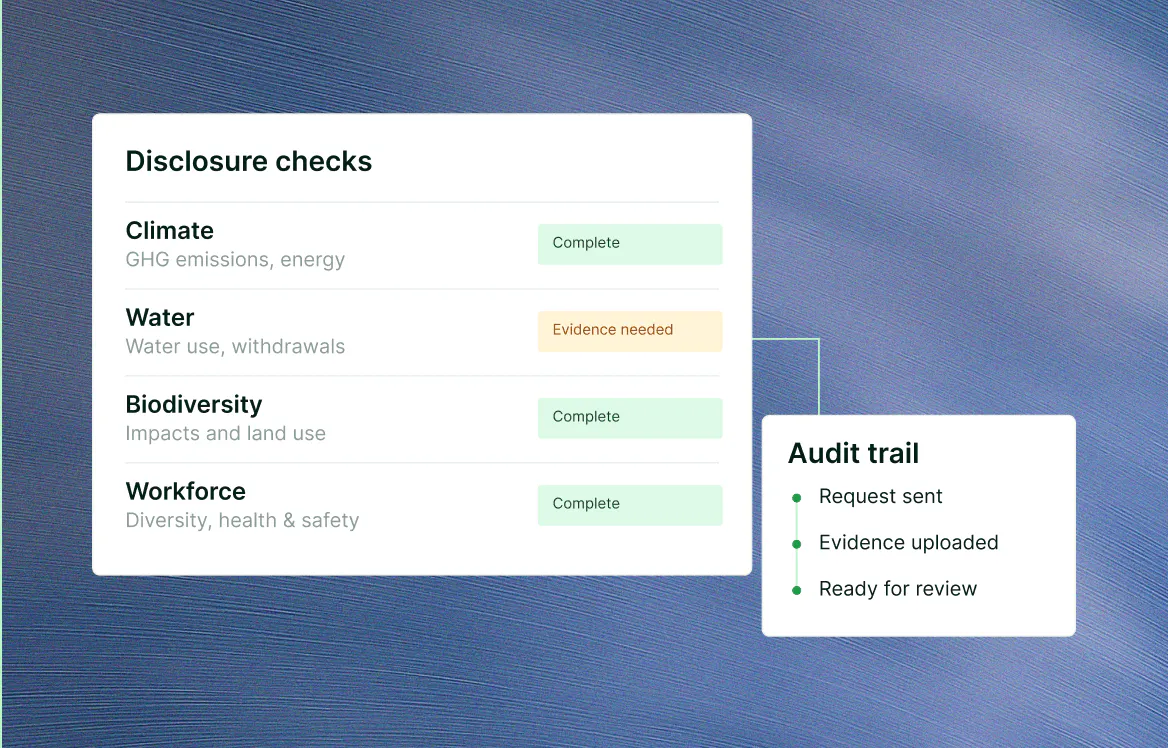
- An ESRS gap analysis shows which material disclosures still lack data, owners or evidence.
- Internal data audits flag inconsistent or unsupported values before they reach the statement.
- Regular check-ins with Greenly CSRD experts keep your filing on track.
- Your auditor gets read-only access to the trail behind every reported figure.
Generate the audit-ready statement
- Export your sustainability statement in XHTML with XBRL tagging, ready to file with your annual report.
- Produce the board summary from the same validated dataset as the statement.
- Reuse the same data for EcoVadis, IFRS S2 and California SB 253 requests, without collecting it twice.

Still have questions?
Check out our complete FAQs in the Knowledge Base to get the answer you’re looking for.
Yes, in two cases. An EU subsidiary of a US group must report if it has over 1,000 employees and over €450M in net revenue. The US parent must report at group level if it earns more than €450M in net EU revenue for two consecutive years and has an EU subsidiary or branch with over €200M in revenue.
EU subsidiaries of US groups report on FY2027 data, published in 2028. US parent companies report on FY2028 data, published in 2029. These dates follow the Omnibus I Directive, in force since March 18, 2026. The consolidated reporting exemption does not cover two cases: large EU public-interest entities (PIEs) and entities falling under Article 40a (ultimate non-EU parent scope).
A double materiality assessment (DMA) identifies which sustainability topics a company must report under CSRD. It scores each impact, risk and opportunity (IRO) on two axes: the company's impact on people and the environment, and the financial effect of sustainability issues on the company. Only material topics are disclosed.
Yes. CSRD sustainability statements require limited assurance from an external auditor or accredited assurance provider in the EU. The planned move to reasonable assurance is currently on pause.
Yes, within a cap. A company in CSRD scope can ask suppliers with fewer than 1,000 employees only for the information set out in the voluntary VSME standard: up to 23 datapoints, or 9 for companies with 10 employees or fewer.